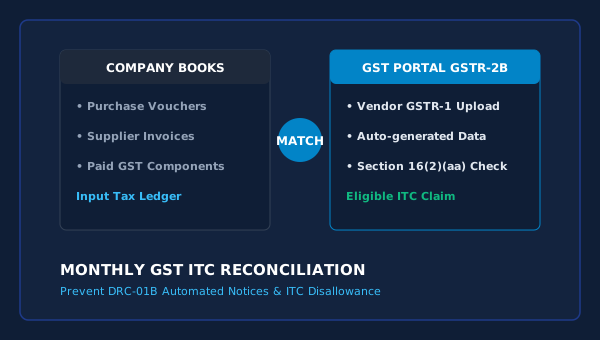
Input Tax Credit (ITC) represents one of the largest working capital levers for Indian enterprises. However, under Section 16(2)(aa) of the CGST Act, no taxpayer can claim ITC unless the invoice has been uploaded by the vendor in their GSTR-1 and is reflected in the recipientÔÇÖs GSTR-2B statement.
The Real Hazard of Claiming Ineligible ITC
Claiming ITC that does not appear in auto-generated GSTR-2B leads to automated DRC-01B notices issued by the GST portal. Taxpayers are given a strict 7-day window to either pay the differential tax with 18% annual interest or provide satisfactory reconciliation explanations. Failure to respond can result in immediate blocking of GSTR-1 filing capabilities.
Best Practices for Monthly Reconciliation
- Enforce Vendor Compliance Deadlines: Require all vendors and suppliers to file their GSTR-1 by the 11th of each month.
- Tie Invoice Payments to GSTR-2B Reflection: Hold back GST amounts or implement payment terms conditioned on the invoice reflecting in your companyÔÇÖs GSTR-2B.
- Perform Automated Matching: Utilize dedicated reconciliation software to detect vendor GSTIN typos, date discrepancies, and taxable amount variances.